
Performance, Commentary & Portfolio
ISIN GB0001490001 | SEDOL 0149000
Fund Manager’s Review
September was about bonds, oil and AI. Negotiations between the United States and Iran to end the conflict in the Gulf remained at an impasse amid renewed hostilities sending the oil price back above $100 a barrel. These prices pale in comparison with those for refined products, where market tightness is most acute. The price of diesel in the US exceeded an unprecedented $200 a barrel during the month, for example. With strategic reserves – the buffer - now much depleted vs pre-war levels, the odds of a more extreme price spike continue to increase.
Higher energy prices impact inflation and inflation expectations. This pushes up interest rates. Combined with a booming AI capital investment cycle, whose vast financing requirements crowd out lending elsewhere, the government’s cost of borrowing rises and, with it, the cost of borrowing across the wider economy. Government bond yields around the world hit multi decade highs. In stark contrast to recent times, money has a cost again. For those countries with high debt and high deficits, debt affordability becomes a concern. This risks a doom loop, whereby higher interest rates increase the risk of default, necessitating a higher interest rate in compensation, ad infinitum. France, which hasn’t run a balanced budget since 1974, is a focus of concern at present, but many Western governments are in the same boat. Whether Prime Minister Andy Burnham likes it or not, indebted governments who need to borrow more are always ‘in hock’ (beholden to) to the bond market.
Certain equity sectors tend to follow the bond markets. Banks, for example, generally prefer higher interest rates, within reason. Customer deposits are often invested in government bonds, so when the bond yields are higher they tend to earn more. Sectors that rely on debt finance, such as real estate and utilities, see their interest cost rise and profits fall commensurately. In September, sector performance followed this logical pattern.
|
The core debate – whether there is sufficient demand to sustain $1.5 trillion per annum of capital expenditures - remains unresolved. |
Perhaps surprisingly, given their increasing reliance on debt finance, AI related stocks fared well during the month. The AI build-out remains controversial, and thus the stocks continue to be volatile. After the summer sell-off there was a modest rebound during the month. The core debate – whether there is sufficient demand to sustain $1.5 trillion per annum of capital expenditures - remains unresolved.
At present, we tend to lag the benchmark when AI related stocks – now a large part of the market – does well. This month was no different. Brunner’s Net Asset Value (NAV) total return for September was -1.16%, versus 0.26% for the benchmark. Whilst our tech names like Taiwan Semi, Microchip, ASML and the recently acquired Meta and Seagate contributed to our performance, not owning index giants like Nvidia, AMD and Apple hurt relative performance. After a strong bounce earlier in the summer, names we hold like Intuit and Booking Holdings, which the market lazily puts in the AI loser basket, also retreated.
Quite frankly, we were surprised by the strength of global markets given what is happening in debt markets; the cost of money is a key input into equity valuations. This is partially down to the robust performance of a few tech mega-caps which continue to defy gravity, supporting the broad market level. Simultaneously, a far greater number of lesser but nevertheless significant businesses saw their value fall during the month. This is starkly illustrated by the performance of the US S&P500 Equal Weight Index, which differs from the traditional S&P500 Index where weightings are determined primarily by the company’s value, and underperformed by about 5% during the month – a huge amount for such a short period. For the time being, the likes of Apple exist in a different realm to the rest of the mere mortals. We admire Apple hugely but fail to see how the current, very rich valuation will permit a decent investment outcome in the coming years, so we are content to remain on the sidelines.
Aside from us continuing to sell-down our holding in accountancy firm CBIZ, which Grant Thornton intend to acquire, there were no trades during the month.
https://www.youtube.com/@AllianzGIInvTrusts
Julian Bishop & James Ashworth
8 October 2026
This is no recommendation or solicitation to buy or sell any particular security. Any security mentioned above will not necessarily be comprised in the portfolio by the time this document is disclosed or at any other subsequent date.
1. Source: AIC, as at the Trust’s Financial Year End (31.11.2025). Ongoing Charges (previously Total Expense Ratios) are published annually to show operational expenses, which include the annual management fee, incurred in the running of the company but excluding financing costs.
Registrations |
|
|
Company No. |
00226323 |
|
FATCA GIIN No. |
EW9PUZ.99999.SL.826 |
Codes |
|
|
RIC |
BUT.L |
|
SEDOL |
0149000 |
|
ISIN |
GB0001490001 |
Awards & Ratings
Association of Investment Companies ISA Millionaire 2026: The AIC ISA Millionaire recognises Investment Trusts that would have made investors more than £1 million if they had invested the full annual ISA allowance in the same trust each year.
Boring Money Rated Investment Trust 2026: The Brunner Investment Trust has been recognised by Boring Money for its performance, governance and approach to communicating with retail investors.
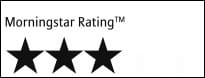
Morningstar Rating: The Morningstar Rating is an assessment of a fund’s past performance – based on both return and risk – which shows how similar investments compare with their competitors. A high rating alone is insufficient basis for an investment decision.
A ranking, a rating or an award provides no indicator of future performance and is not constant over time.